Official 2026 Rate
PhilHealth Contribution 2026 | Rates and How to Compute
Your whole premium comes down to one number. For 2026 the PhilHealth contribution rate is 5 percent of monthly basic salary. Here is the full table, a calculator, and how to compute your share.
2026 at a glance
Rate
5%
Split
50 / 50
Minimum
₱500
Maximum
₱5,000
Floor ₱10,000 · Ceiling ₱100,000
Your whole PhilHealth premium comes down to one number and one rule. For 2026 the PhilHealth contribution rate is 5 percent of your monthly basic salary, and where you land on the table decides the peso amount. Get that number right and the rest is simple.
This is the complete guide to the PhilHealth contribution 2026 edition. We give you the official rate, the full PhilHealth contribution table 2026, a calculator that does the math for you, and clear steps for how to compute your share whether you are employed, self employed, a voluntary member, or an OFW. We also cover how to check your PhilHealth contribution online, how to pay, and exactly what happens if you miss a month.
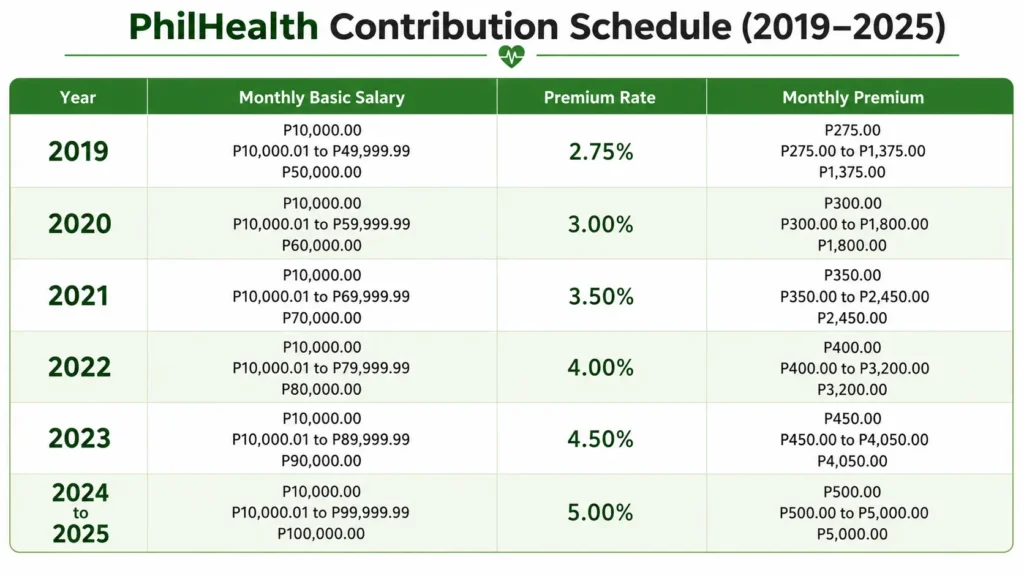
For 2026 the PhilHealth contribution rate is 5 percent of monthly basic salary. The income floor is 10,000 pesos, so the lowest premium is 500 pesos, and the income ceiling is 100,000 pesos, so the highest premium is 5,000 pesos. Employed members split the 5 percent equally with their employer, 2.5 percent each. Self employed, voluntary, and OFW members pay the full 5 percent themselves.
What Is a PhilHealth Contribution?
A PhilHealth contribution is the monthly premium you pay to keep your PhilHealth membership active. Think of it as your ticket to ride. Every peso goes into one national fund, and that pooled money is what pays members hospital bills, outpatient benefits, and other claims when they need care. When you pay, you stay covered.
You will see it written a few different ways, and they all mean the same thing. People often ask what is PHIC contribution, and the answer is simple: it is the PhilHealth Insurance Corporation premium, since PHIC is the agency short name.
And an NHIP contribution refers to the same payment under the National Health Insurance Program, the program PhilHealth runs. So a PHIC contribution, an NHIP contribution, and a PhilHealth contribution are three names for the one premium you pay each month.
The amount is not random. It is a fixed percentage of your income, set by law and adjusted on a schedule under Republic Act 11223, the Universal Health Care Act. That is why people search for the philhealth premium or the exact philhealth monthly contribution for their salary, because the figure changes with what you earn, up to a cap.
Who Is Required to Pay PhilHealth Contributions?
Membership is mandatory for almost everyone under the Universal Health Care Act, but how you pay depends on your category. Here is where you fit.
So whether you are on a payroll or paying as a philhealth contribution for self employed member, you have a category, and that category sets how much you pay and who pays it.
The PhilHealth Contribution Rate 2026 (Official 5 Percent)
The philhealth contribution rate 2026 is 5 percent of your monthly basic salary. This is the final rate scheduled under the Universal Health Care Act, and it applies across the year. Two limits shape it. The income floor is 10,000 pesos, and the income ceiling is 100,000 pesos.
In plain terms, if you earn 10,000 pesos or less, your premium is fixed at 500 pesos. So the minimum PhilHealth contribution for 2026 is 500 pesos a month. If you earn between 10,000 and 100,000 pesos, you pay 5 percent of that salary. And if you earn 100,000 pesos or more, your premium is capped at 5,000 pesos no matter how much higher your salary goes.
Editor’s take
A lot of readers arrive confused about whether the rate is 5 percent or 5.5 percent. For 2026, the correct, official figure is 5 percent. Some older tables and outdated guides still show 5.5 percent or a 50,000 peso ceiling, and following those will give you the wrong number. Use 5 percent, a 10,000 peso floor, and a 100,000 peso ceiling, and you will match what PhilHealth actually applies.
The Official PhilHealth Contribution Table 2026
This is the section most people come for, and the one both major competitors either skip or get wrong. Below is the full philhealth contribution table 2026 at 5 percent, showing the total monthly premium and, for employed members, the equal split between you and your employer.
| Monthly Basic Salary | Rate | Total Monthly Premium | Employee Share | Employer Share |
|---|---|---|---|---|
| ₱10,000 and below | 5% | ₱500 | ₱250 | ₱250 |
| ₱15,000 | 5% | ₱750 | ₱375 | ₱375 |
| ₱20,000 | 5% | ₱1,000 | ₱500 | ₱500 |
| ₱25,000 | 5% | ₱1,250 | ₱625 | ₱625 |
| ₱30,000 | 5% | ₱1,500 | ₱750 | ₱750 |
| ₱40,000 | 5% | ₱2,000 | ₱1,000 | ₱1,000 |
| ₱50,000 | 5% | ₱2,500 | ₱1,250 | ₱1,250 |
| ₱70,000 | 5% | ₱3,500 | ₱1,750 | ₱1,750 |
| ₱90,000 | 5% | ₱4,500 | ₱2,250 | ₱2,250 |
| ₱100,000 and above | 5% | ₱5,000 | ₱2,500 | ₱2,500 |
Two notes that save people from errors. First, PhilHealth is computed on your monthly basic salary, not your gross pay. Overtime, allowances, and bonuses such as the 13th month pay are excluded. Second, the floor and ceiling are hard limits, so a salary below 10,000 pesos still pays the 500 peso minimum, and a salary above 100,000 pesos never pays more than the 5,000 peso maximum.
How to Compute Your PhilHealth Contribution
If you are wondering how much contribution for PhilHealth you actually owe and would rather do the math yourself, here is how to compute PhilHealth contribution for every member type. The base formula is the same for everyone: monthly basic salary multiplied by 5 percent equals your total monthly premium. What changes is who splits it.
For Employed Members (50/50 Split)
Employed members share the premium equally with their employer. You each pay half of the 5 percent, which is 2.5 percent of your basic salary. Take a salary of 30,000 pesos. Five percent is 1,500 pesos total. Split it in half and your share is 750 pesos, with your employer paying the other 750 pesos.
Your 750 is what gets deducted from your payslip, and your employer remits the full 1,500 to PhilHealth. On some payslips this line is labelled the EE NHIP contribution, which just means the employee share under the National Health Insurance Program, so if you see EE NHIP on your slip, that is your 2.5 percent.
For Self Employed and Voluntary Members
Self employed and voluntary members pay the full 5 percent themselves, because there is no employer to share it. If you declare a monthly income of 20,000 pesos, your contribution is 5 percent of that, which is 1,000 pesos, and you pay all of it. This is the number most people mean when they compute a philhealth voluntary contribution.
For OFWs
The philhealth contribution for OFW works the same way as a voluntary member, at the full 5 percent of declared monthly income, within the same floor and ceiling. Land based OFWs typically pay directly, while sea based OFWs often have their share arranged through their manning agency. Either way the rate is 5 percent.
If You Earn Below ₱10,000 or Above ₱100,000
These two edges are simple. Earn 10,000 pesos or less and you pay the fixed floor of 500 pesos. Earn 100,000 pesos or more and you pay the capped ceiling of 5,000 pesos. The 5 percent only moves your premium for salaries between those two points.
PhilHealth Contribution Calculator
Rather not reach for a calculator app? Use ours. Enter your monthly salary, choose whether you are employed or paying on your own, and it returns your total premium, your share, and your annual total instantly. It uses the exact 2026 figures above, so what you see is what PhilHealth applies.
How it works
The calculator multiplies your monthly basic salary by the 5 percent rate, applies the 500 peso floor and 5,000 peso ceiling, and, if you are employed, halves the result to show your 2.5 percent share. In this JSON import the calculator is preserved as an editable native visual panel because the v0.4.1 importer schema does not support form inputs or JavaScript.
Whichever way you count it, the philhealth contribution calculator is the fastest way to turn your salary into the exact peso figure you owe each month.
How to Check Your PhilHealth Contribution Online
Once you are paying, you will want to confirm the payments are actually posted to your record. Here is how to check PhilHealth contribution online so nothing slips through the cracks.
Check Through the PhilHealth Member Portal
- Go to the PhilHealth Member Portal and log in with your registered account, or create one if you have not yet.
- Open your member profile and look for the premium contributions or contribution history section.
- Review the posted months to confirm your payments appear and the amounts are correct.
If you have not set up your online account yet, our PhilHealth Login guide walks you through registering and signing in to the Member Portal step by step.
Other Ways to Verify (Hotline, Email and Branch)
If the portal is down or your payment is not showing, you can confirm your philhealth contribution inquiry another way. Call the PhilHealth hotline, email the official action center, or visit your Local Health Insurance Office with a valid ID. Keep your payment receipts, because they are your proof if a posting is delayed.
How to Pay Your PhilHealth Contribution
Paying is the easy part once you know your amount. There are several channels, so pick the one that fits how you like to transact.
What Happens If You Miss a PhilHealth Contribution?
Missing a month is not the end of the world, but it is not free of consequences either, so it pays to understand it. Your PhilHealth membership does not get cancelled the moment you skip a payment, yet unpaid months can leave gaps that affect your eligibility for certain benefits, which often look at whether you have paid a required number of months within a set period before a claim.
For voluntary and self employed members, PhilHealth generally allows you to settle missed months, though there can be limits on how far back you can pay and conditions on paying retroactively. The safe habit is not to let a backlog form in the first place. If you know a benefit is coming, such as a planned hospital stay or maternity, make sure your recent contributions are complete and posted well ahead of time.
Pro tip
Do not wait until you need to file a claim to check your record. Log in every few months, confirm your contributions are posted, and settle any gap early. A five minute check now can save you a denied claim later.
Why Your Contributions Matter (What You Get Back)
It is easier to pay when you can see what the premium buys. Your PhilHealth contribution is not a tax that disappears. It keeps you eligible for a real set of benefits.
Because eligibility usually depends on having paid a required number of months, staying current is what makes sure the coverage is there the day you actually need it. That is the real reason the philhealth monthly contribution is worth paying on time.